For three days later this month, full-size homes will sit on the National Mall. HUD announced the sponsors and accepted exhibitors for its 2026 Innovative Housing Showcase on September 10, with the public event scheduled for September 22 through 24 in Washington. The lineup is expected to include manufactured, modular and 3D-printed housing alongside building components and construction technologies.
That is worth watching from Northern Wisconsin. Factory production, component framing and other controlled construction methods can reduce weather exposure, organize labor and make a home plan easier to repeat. A person walking through a finished model can also see something a policy memo cannot show: these are real houses with ordinary kitchens, bedrooms, mechanical systems and materials—not abstract units on a housing chart.
But a demonstration home arrives in Washington under demonstration conditions. It does not have to carry the full cost of a subdivision street in Oneida County, cross a tight turn between pines in Vilas County or connect to a private septic system in Forest County. The useful Northwoods question is not whether a model looks good on the Mall. It is whether the entire property can be delivered, installed, financed and owned at a monthly cost connected to local incomes.
What the showcase can prove
The showcase can help separate construction innovation from construction stereotypes. HUD’s announcement says visitors will see full-scale manufactured, modular and 3D-printed models built by American companies. Those labels describe different processes and code paths, but each can produce permanent housing when the home and site are designed for that result. The event should give officials, lenders and buyers a chance to look at workmanship and ask specific questions instead of debating a category from memory.
This is also a significant year for manufactured housing. The industry is marking 50 years of the federal HUD Code, the national construction and safety standard for manufactured homes. That standard governs the home leaving the factory. It does not choose the parcel, approve the local land use, design every foundation or guarantee a particular mortgage. A federal code can make production consistent while the completed property still depends on coordinated local work.
Innovation should therefore be judged by the constraint it actually removes. Factory construction may reduce framing time or weather delays. Wall panels may make scarce site labor more productive. A compact CrossMod or modular plan may put useful living space on a smaller footprint. None of those advantages automatically pays for unsuitable soil, an overlong driveway, a utility extension or financing carried while approvals are unresolved.
Where the Northwoods work begins
The Northwoods work begins at the property line. Before a home is selected, the development team needs a survey, zoning path, access plan and a credible understanding of wetlands, topography, soils and drainage. On an unsewered site, the well, primary septic area and replacement area have to fit with the home, driveway and setbacks. In a serviced neighborhood, the question shifts to the cost and capacity of roads, water, sewer, stormwater and utility distribution.
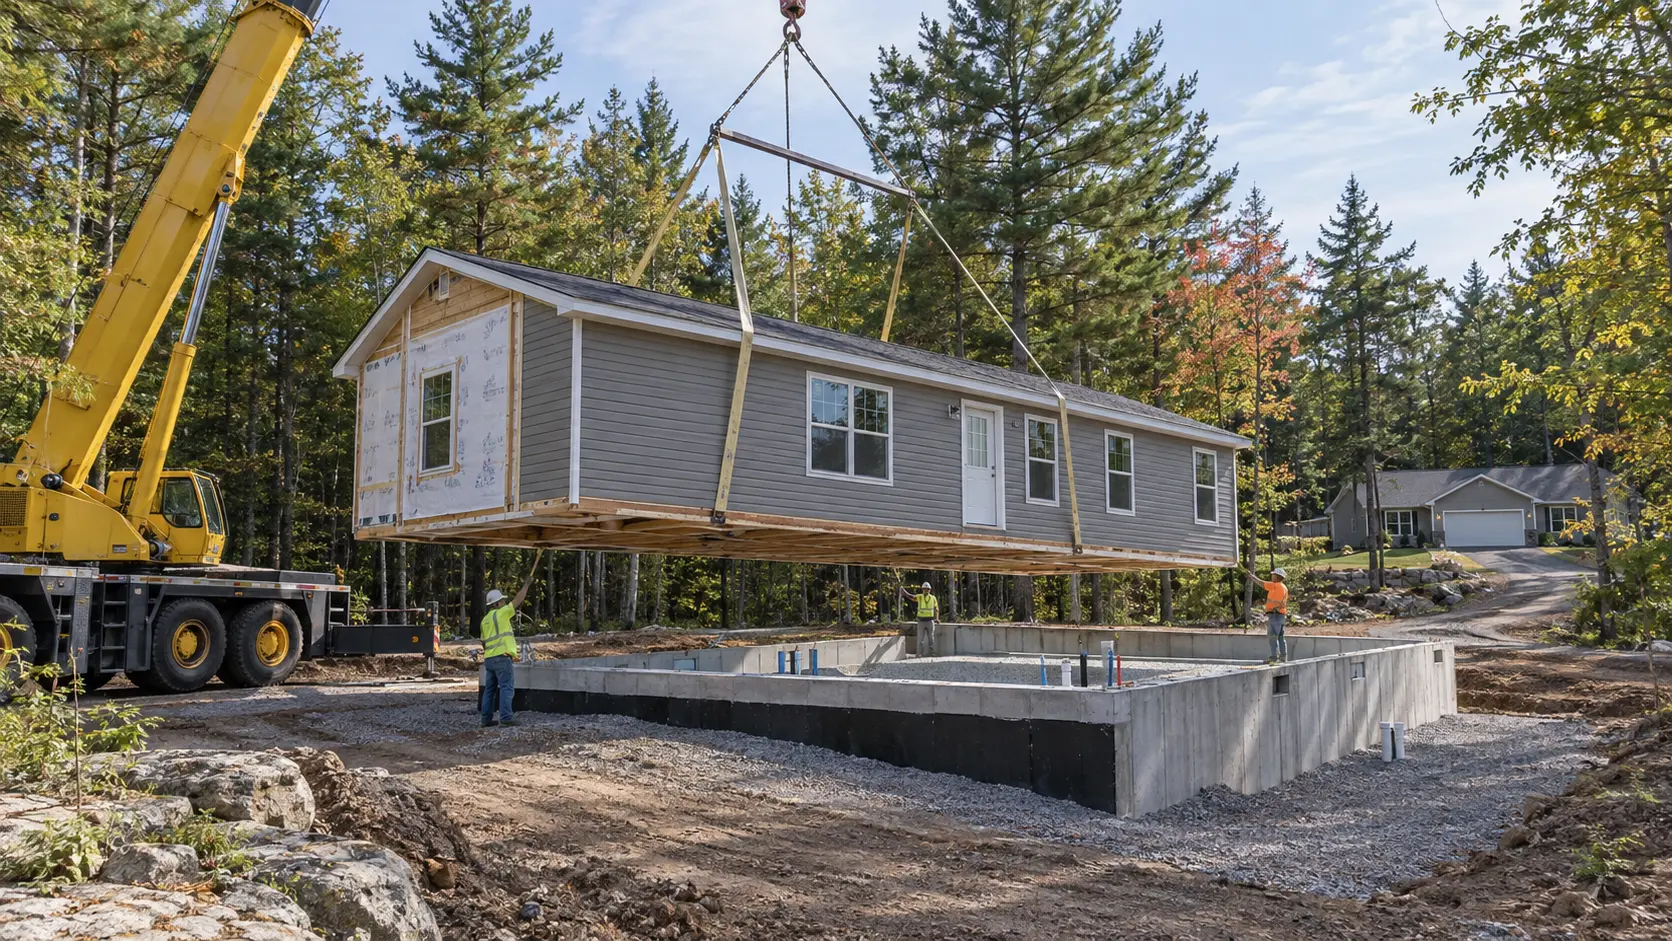
Delivery is a design input, not a last-week logistics problem. A manufactured or modular section may be much larger than an ordinary truck load. The route, final turns, overhead wires, slopes, crane or roller position and temporary staging area all need to be checked while the site plan can still change. A home that fits neatly between setback lines can still be impossible—or unnecessarily expensive—to place.
The foundation must match the exact home and the ground beneath it. Frame loads, marriage-line supports, openings, anchors, frost protection and utility penetrations need to be coordinated before concrete. Northern Wisconsin frost and variable soils make generic warm-climate details especially risky. Repetition can lower cost, but only after an engineered base detail defines which site or home conditions require a change.
The monthly-payment test
The finished property also has to make sense to a lender and appraiser. Title treatment, permanent installation, comparable sales, foundation documentation and the selected loan program can affect the path. The financing conversation belongs before the order, because a technically impressive home does not expand ownership if the buyer discovers late that the property does not fit the expected mortgage or valuation approach.
This week’s mortgage benchmark makes that discipline visible. Freddie Mac reported on September 10 that the average 30-year fixed rate was 6.76 percent, up from 6.71 percent the previous week and 6.35 percent a year earlier. It is a national average drawn from thousands of loan applications, not a guaranteed quote for a Northwoods buyer. Freddie Mac describes its benchmark profile as an owner-occupied, one-unit purchase with good or excellent credit and 20 percent down.
To illustrate price sensitivity rather than predict a loan offer, applying 6.76 percent to a 30-year term makes each additional $10,000 financed worth roughly $65 per month in principal and interest. Financing 95 percent of a $250,000 completed property would be about $1,542 per month under that simple assumption; at $300,000, it would be about $1,850. A five-percent-down borrower might receive a different rate, and taxes, insurance, mortgage insurance, utilities and association charges would come on top.
Questions worth bringing home
That is why saving money on the house while losing it on the site does not create affordability. An extra $20,000 for rock excavation, a long electrical run or an undersized first phase is not merely a line in a development budget. If financed on similar terms, it is about $130 per month before the other ownership costs. Product innovation matters most when its savings survive all the way to the completed price.
The 2025 Oneida County Housing Study gives that price discussion a local target. It identifies owner-occupied homes priced from $200,000 to $299,000 as a high-priority need for households earning $75,000 to $99,000, and more than 85 percent of surveyed home seekers said single-family homes for purchase were the hardest type to find. The report estimates a need for as many as 1,358 additional housing units by 2030. A showcase home is relevant here only if it can help a complete project reach those kinds of buyers.
Anyone evaluating the new models should come home with more than a brochure. What is included in the quoted home price? Which foundation and installation assumptions were used? What is the design roof load? How wide and tall are the transport sections? Who owns delivery risk? Which site work must be complete before arrival? What documentation will the lender, appraiser, insurer and local inspector receive? Which options change the final cost most?
Innovation that can repeat
Communities should ask a parallel set of questions. Do local ordinances treat permanent factory-built homes according to measurable design and installation standards? Are compliant projects approved predictably? Which publicly or privately controlled parcels have been screened for access and utilities? Can infrastructure be phased across enough homes to keep each finished lot inside the target price? Is there a state or local tool that reduces cost rather than simply moving it to a later year?
The best innovation may be a repeatable sequence rather than a dramatic material. One home plan, one coordinated foundation family, a known delivery route, a small group of prepared lots and a financing path understood by local lenders can be more valuable than a prototype nobody can price twice. Each repetition should make the allowance list shorter and the buyer’s complete number more reliable.
Teneleven Development looks at manufactured, modular, CrossMod and other permanent construction options through that complete-project test. The objective is not to bring a Washington exhibit to the Northwoods. It is to identify what the exhibit does well, combine it with buildable land and disciplined site work, and produce durable owner-occupied single-family homes that local buyers can finance and keep.