A factory-built home can be approved as a safe house and still struggle to become an ordinary mortgage. That gap is the reason an executive order signed October 22 deserves attention in Northern Wisconsin. It creates a Task Force on Manufactured Housing Innovation and puts HUD, the Federal Housing Finance Agency, USDA, the Department of Commerce and the Department of Veterans Affairs around the same table.
The order gives the group 180 days to recommend how federal housing programs can better recognize manufactured and other factory-built construction. Its assignment includes common specifications, reciprocal certifications and inspections, fewer duplicative reviews, broader use of federal financing and clearer guidance for modern production methods. This is a work order, not a finished rule.
For Oneida, Lincoln, Vilas and Forest County, that distinction matters. A task force announcement does not make a particular home eligible for a mortgage, approve a Wisconsin installation or override a local zoning decision. It does identify a real barrier: the same permanent home can be evaluated differently depending on which federal program, lender or agency touches the transaction.
Why five agencies matter
HUD administers the national construction and safety standards for manufactured homes. FHFA oversees Fannie Mae and Freddie Mac, whose secondary-market rules influence conventional mortgage availability. USDA and VA operate or support home-loan programs used by rural households and veterans. Commerce participates in standards and manufacturing policy. Each agency approaches the property from a different responsibility, but the buyer experiences all of it as one home purchase.
The problem is not that every program should become identical. Borrower eligibility, credit risk and public purpose legitimately differ. The avoidable problem is asking a manufacturer, developer or buyer to prove the same construction quality several times in formats that do not recognize one another.
The executive order specifically calls for reciprocal recognition of licenses, certifications, approvals and inspections where that can eliminate unnecessary duplication. In practice, useful reciprocity could mean that a documented factory inspection, home certification or approved construction feature travels more cleanly into another federal housing program instead of starting over at the lender's desk.
Reciprocity could remove duplicate work
That would be especially valuable for homes with enhanced design standards. Freddie Mac's CHOICEHome and Fannie Mae's MH Advantage programs are examples of conventional financing paths for eligible manufactured homes with specified features. FHFA's 2025 housing report notes that Freddie Mac began accepting either the MH Advantage sticker or CHOICEHome label as evidence that a home meets the relevant construction elements. That small act of label recognition is the kind of coordination the new task force could extend.
Cross-program recognition does not eliminate the appraisal. It can make the property easier to describe. A lender and appraiser still need the purchase contract, model and specifications, site plan, land ownership, foundation design, utility scope, installation records and the best available comparable sales. The benefit is a clearer file with fewer disagreements about what the home is before anyone analyzes what it is worth.
Financing is built into the task force's mandate rather than left for later. The order directs the group to consider federal insurance, guarantees, purchasing authority and other program tools that could encourage production of affordable factory-built homes. FHFA's presence is important because a mortgage product that cannot be purchased or securitized at scale may remain dependent on a small number of portfolio lenders.
Financing belongs in the same conversation
USDA's role is equally relevant to the Northwoods. Its Section 502 Direct program serves eligible low- and very-low-income rural buyers, while its guaranteed program can support eligible single-family homes through approved private lenders. USDA's published materials already recognize manufactured homes under program rules, but the transaction still depends on property eligibility, permanent installation, title, appraisal and complete site costs.
The same order separately directs USDA and VA, subject to existing law and available appropriations, to reduce rates on their direct single-family loans. That sentence is significant, but it is not a new quoted rate or an automatic reduction for a borrower today. Buyers should rely on each agency's published program terms and a participating lender until implementation details appear.
VA already says an eligible purchase loan may be used for a manufactured home or lot. Its property guidance also treats the manufactured home and site as a real-estate entity under state law and requires compliance with local zoning. Better federal coordination could simplify part of that file, but it will not turn a movable home on an unresolved site into mortgage-ready real estate.
What the order does not change today
The task force must also study whether federal grants can encourage states and local governments to adopt standardized permitting and licensing for factory-built housing. That could reward communities that use objective, repeatable reviews. It does not immediately preempt local land-use authority, and the order itself says implementation remains subject to existing law and available funding.
Wisconsin and Northwoods communities therefore still control much of the finished result. A home needs a legal lot, permitted use, compliant foundation and installation, driveway access, water and wastewater, electrical service, drainage and inspections. Private restrictions, shoreland rules, wetlands and site-specific engineering do not disappear when federal agencies agree on a label.
Oneida County's 2025 housing study explains why removing avoidable friction is worthwhile. It estimates that the county may need up to 1,141 additional owner-occupied homes by 2030. The study also identifies $200,000-to-$299,000 homes as a priority for households earning $75,000 to $99,000 and recommends current comprehensive plans, subdivision and zoning updates, developer outreach and stronger state and regional partnerships.
Build a Northwoods test case now
Those price points leave little room for duplicated professional work or a late financing redesign. If one agency's eligible home needs a different foundation document for another lender, or a certification is discovered to be unusable after the home is ordered, the cost lands somewhere: in the developer's contingency, the buyer's cash requirement, the schedule or the deal that never closes.
Northwoods developers do not need to wait six months to prepare. A useful test case can be assembled now around one available home and one realistic lot. The file should identify the construction standard, model certifications, foundation and installation package, title treatment, local approvals, utility and driveway scope, complete delivered cost and the requirements of at least two plausible mortgage paths.
The next step is a gap table, not a press release. One column should list what HUD requires of the home. Others should list Wisconsin installation documents, municipal permits, appraiser inputs and the lender or federal program conditions. Wherever the same fact is requested twice in a different form, the project has identified exactly the kind of friction the task force is supposed to address.
Municipalities can do a parallel review. They can confirm that permanent HUD-code homes are evaluated through objective standards tied to health, safety, installation and neighborhood performance; publish a predictable permit sequence; and avoid cosmetic rules that exclude an otherwise compliant home without reducing a documented public risk.
The real measure will come after the task force reports. A successful outcome is not simply a shorter federal manual. It is a Northwoods buyer reaching closing with fewer duplicate approvals, a lender understanding the collateral, an appraiser receiving a complete property file and a permanent owner-occupied home meeting the same safety and durability expectations without carrying unnecessary process cost.
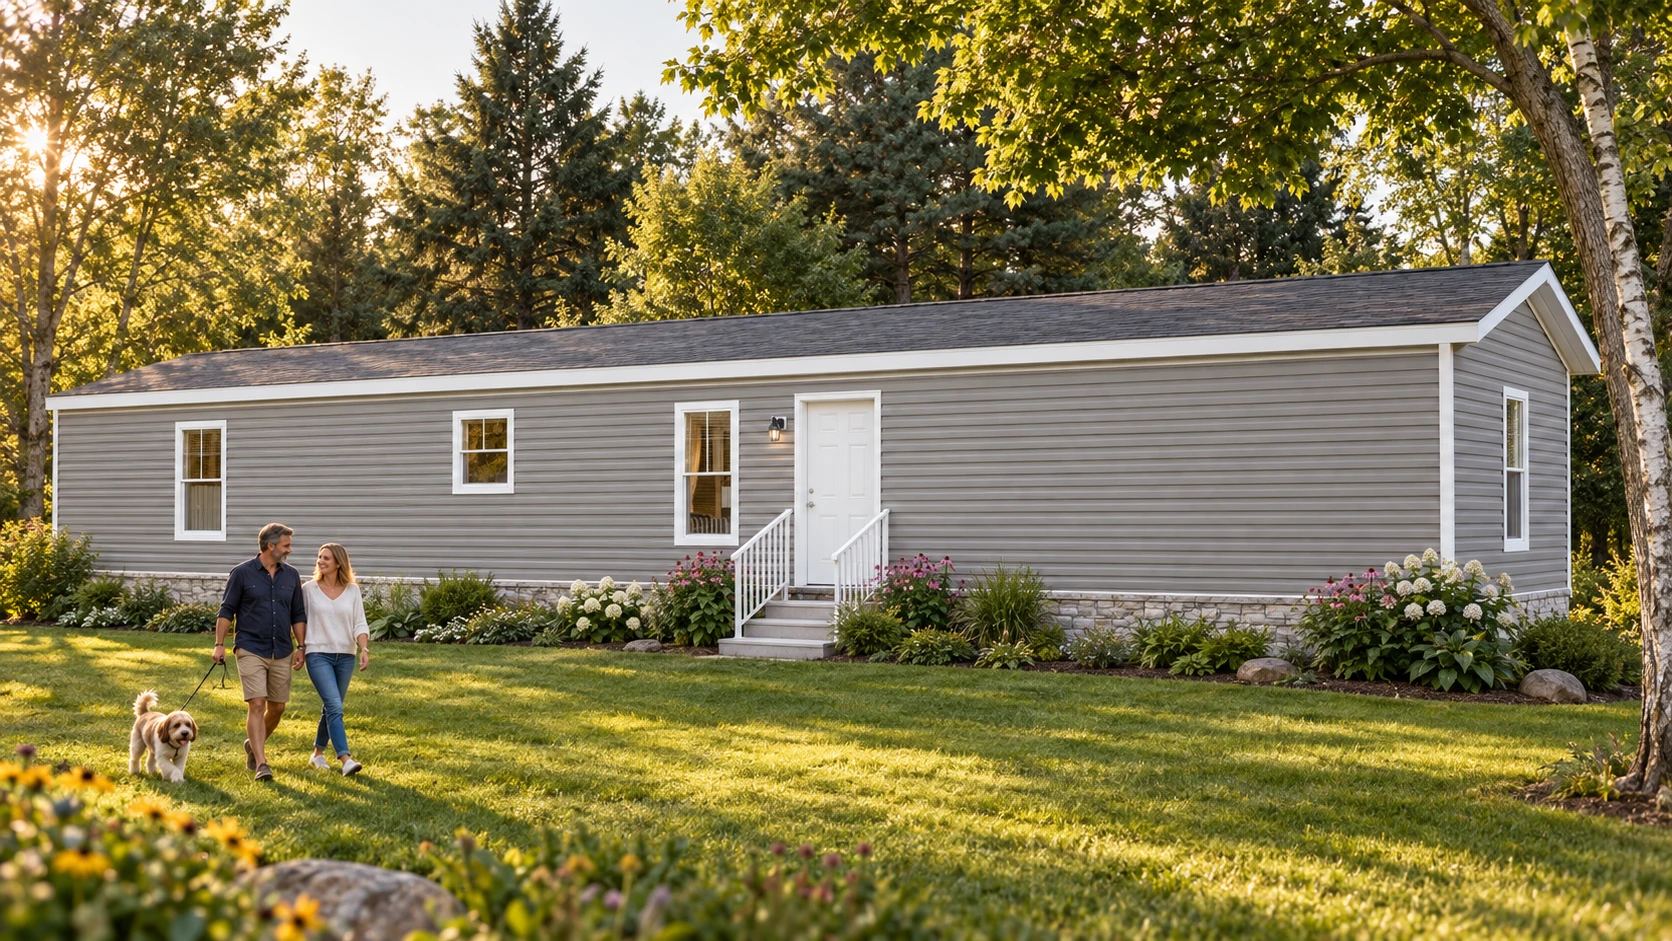
Five agencies are finally looking at the same house. Teneleven Development's interest is in making sure they also see the same complete property: an approved Clayton home, a buildable Wisconsin lot, a documented installation and a financing path that works before construction begins. Coordination at the federal level will matter only when it makes that local sequence clearer, faster and less expensive for the household expected to own the home.